Rayzon Solar IPO: New DRHP Addendum Filed with SEBI — Key Changes, 3.5 GW Capex & Financials
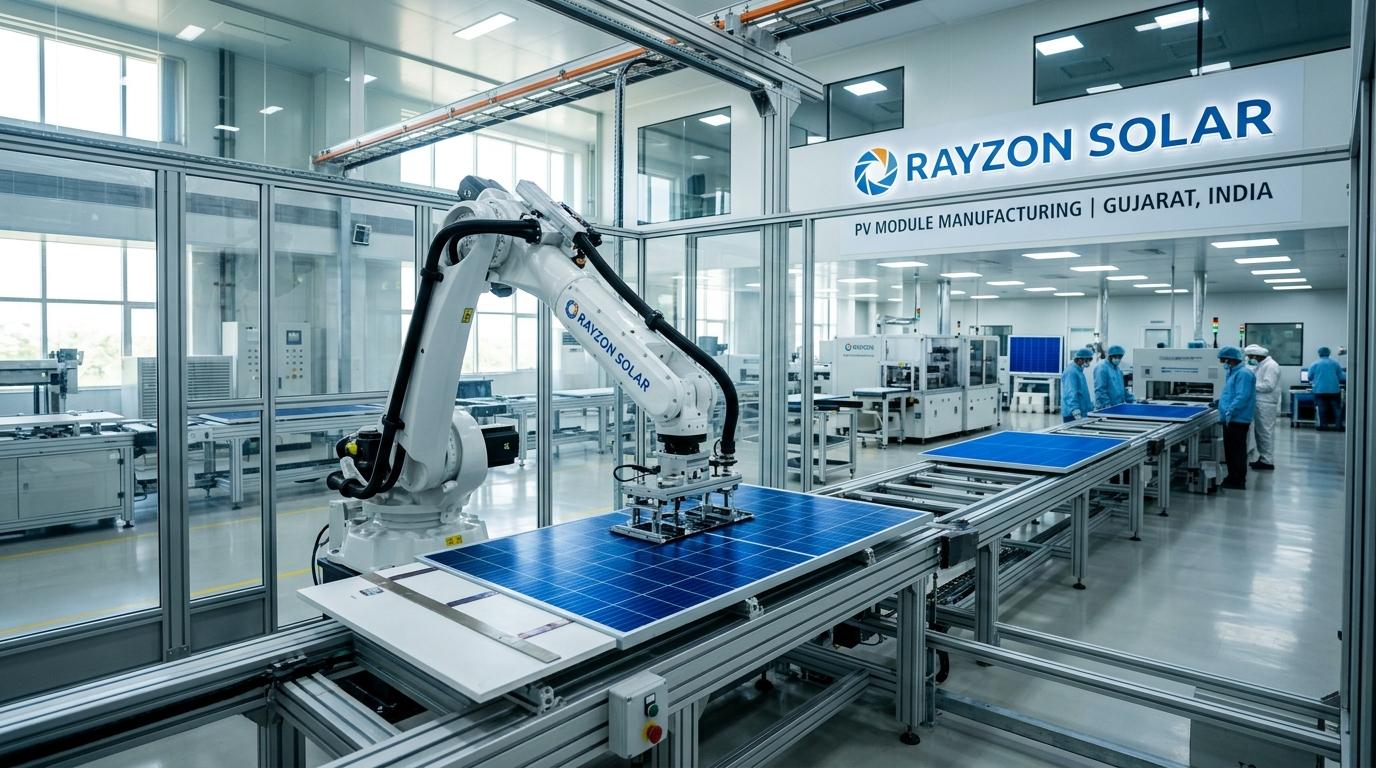
Rayzon Solar Limited, India's second-largest solar photovoltaic (PV) module manufacturer commanding a 7.21% national shipment market share according to JMK Research, has officially submitted an Addendum to its Draft Red Herring Prospectus (DRHP) to the Securities and Exchange Board of India (SEBI) and published offer documents on its Investor Relations portal on 17 September 2026. The regulatory addendum formally incorporates an updated Project Cost Vetting Report and Chartered Engineer's Certificate dated 11 September 2026, detailing the phased capital expenditure required to commission a massive 3.5 GW TOPCon solar cell manufacturing facility in Surat, Gujarat, through its wholly-owned subsidiary, Rayzon Energy Private Limited. The proposed public offering remains structured as a 100% fresh issue of up to ₹1,500 Crore with zero Offer for Sale (OFS) secondary dilution by founding promoters, positioning the enterprise for end-to-end solar supply chain integration under India's renewable energy manufacturing boom.
1. The Regulatory Milestone: Rayzon Solar Files DRHP Addendum on 17 September 2026
Marking an essential regulatory and commercial milestone in India's clean energy manufacturing capital markets, Rayzon Solar Limited has officially submitted an Addendum to its Draft Red Herring Prospectus (DRHP) to the Securities and Exchange Board of India (SEBI) and published updated offer documents on 17 September 2026.
Founded in 2017 in Surat, Gujarat, Rayzon Solar has emerged as one of the country's fastest-scaling solar photovoltaic (PV) module manufacturing powerhouses. The submission of an Addendum is a formal statutory procedure governed under the SEBI (Issue of Capital and Disclosure Requirements) Regulations, 2018, utilized by prospective issuers to provide updated material disclosures, third-party technical validations, and refined project timelines before registering the final Red Herring Prospectus (RHP) with the Registrar of Companies (RoC).
Investors should recognize that an Addendum reflects advanced regulatory positioning: it validates updated project execution parameters for its massive 3.5 GW solar cell backward integration, confirming that the company is actively preparing for public market entry.
| Statutory Parameter | Disclosed Regulatory Specification | Editorial & Verification Context |
|---|---|---|
| Issuer Corporate Entity | Rayzon Solar Limited | Headquartered in Surat, Gujarat (Founded in 2017) |
| Statutory Filing Category | Addendum to the Draft Red Herring Prospectus | Submitted to SEBI under ICDR Regulations on 17 Sept 2026 |
| Core Business Segment | Solar Photovoltaic (PV) Module Manufacturing | High-efficiency TOPCon and Mono-PERC solar modules |
| Total Issue Structure | Up to ₹1,500 Crore | 100% Pure Fresh Capital Issuance |
| Offer for Sale (OFS) | Nil (Zero Shares) | Zero secondary promoter dilution |
| Equity Face Value | ₹10 per Equity Share | Standard denomination for Mainboard offerings |
| Domestic Market Standing | Ranked #2 in India (7.21% Market Share) | Verified via JMK Research & Analytics FY26 Shipment Report |
| Proposed Listing Venues | BSE & NSE Mainboard | Dual national stock exchange trading debut |
| Book Running Lead Managers | D&A Financial Services, Nuvama, Motilal Oswal | Syndicate managing book building & marketing |
| Registrar to the Issue | MUFG Intime India Private Limited | Formerly Link Intime India; handles allotment & refunds |
2. What Has Changed in Rayzon Solar's 17 September 2026 DRHP Addendum?
An Addendum serves to inform institutional and retail investors of critical developments that occurred after the initial DRHP was submitted. A detailed comparative review reveals four major statutory updates:
| Disclosed Parameter | Original DRHP Baseline | Updated 17 September 2026 Addendum Status |
|---|---|---|
| Project Cost Vetting | Preliminary in-house project budget estimates | Formal Project Cost Vetting Report dated 11 September 2026 conducted by an independent institutional consultant |
| Technical Validation | Architectural equipment blueprints | Comprehensive Chartered Engineer's Certificate dated 11 September 2026 validating plant layout and machine throughput |
| 3.5 GW Solar Cell Capex | Broad subsidiary capital infusion roadmap | Fine-tuned quarterly drawdown milestones for civil construction and cleanroom machinery procurement |
| Market Share Verification | General internal industry projections | Formal inclusion of JMK Research & Analytics shipment rankings confirming #2 national position |
3. Backward Integration Strategy: The 3.5 GW TOPCon Solar Cell Plant in Surat
The core strategic rationale behind Rayzon Solar's ₹1,500 Crore public issue is aggressive backward integration.
Currently, the vast majority of Indian solar module manufacturers operate as assemblers: they import silicon solar cells (predominantly from China, Vietnam, and Malaysia), string them together with ethylene-vinyl acetate (EVA) encapsulant sheets and solar glass, and assemble finished solar PV modules. This structure leaves domestic manufacturers vulnerable to international cell price spikes, currency swings, and anti-dumping tariff revisions.
To eliminate this structural vulnerability, Rayzon Solar is establishing a state-of-the-art 3.5 GW TOPCon (Tunnel Oxide Passivated Contact) solar cell manufacturing facility in Surat, Gujarat:
- Subsidiary Investment: Capital will be infused directly into wholly-owned subsidiary Rayzon Energy Private Limited, which is overseeing project engineering and civil plant erection.
- Captive Supply Security: The 3.5 GW cell line will meet the captive raw material needs of Rayzon's expanding module capacity, ensuring uninterrupted production schedules for utility-scale EPC developers.
- EBITDA Margin Expansion: Producing solar cells in-house captures the manufacturing margin previously surrendered to foreign cell suppliers, structurally expanding operating EBITDA margins.
- ALMM & Domestic Content Compliance: Domestic cell production satisfies strict Domestic Content Requirement (DCR) tenders issued by SECI, NTPC, and state utilities, granting Rayzon priority access to government-backed solar projects.
4. Market Standing: How Rayzon Solar Became India's #2 Solar Module Shipper
According to the newly incorporated industry benchmark report by JMK Research & Analytics for FY 2025–26, Rayzon Solar achieved an unprecedented operational surge:
- 7.21% National Market Share: Rayzon Solar shipped over 1.8 GW of solar modules in FY26, securing the **#2 ranking nationwide** in total module shipments behind industry leader Waaree Energies.
- Approved List of Models and Manufacturers (ALMM): Rayzon's manufacturing facilities are fully enlisted under the Ministry of New and Renewable Energy (MNRE) ALMM mandate, allowing its modules to be deployed across all grid-connected and subsidized rooftop installations.
- Expansion under PM Surya Ghar Muft Bijli Yojana: The central government's residential rooftop solar initiative targeting 10 million households has generated massive demand for Rayzon's high-efficiency 550W+ bifacial TOPCon panels across western and northern India.
- Export Diversification: Beyond domestic utility solar, Rayzon has expanded module exports to North America, Europe, and the Middle East, capitalizing on global supply chain de-risking away from Chinese manufacturing.
5. Stated Objects of the ₹1,500 Crore 100% Fresh Capital Issue
From an institutional corporate finance perspective, the issue structure is highly favorable to incoming public shareholders because it is a 100% Fresh Issue with zero secondary Offer for Sale (OFS) cash-out by promoters Chiragkumar Patel and Hardikkumar Patel.
| Strategic Object of the Issue | Targeted Capital Outlay | Expected Corporate & Balance Sheet Impact |
|---|---|---|
| Investment in Subsidiary (Rayzon Energy) | Major portion of net fresh proceeds | Part-financing civil works, cleanrooms, and automated wafer-diffusion lines for the 3.5 GW TOPCon solar cell plant in Surat |
| Working Capital Augmentation | Operational liquidity allocation | Financing bulk procurement of high-purity polysilicon wafers, specialized silver paste, and tempered solar glass |
| Debt De-leveraging | Prepayment / repayment of credit facilities | Reduces interest finance expenses and enhances debt service coverage ratios (DSCR) |
| General Corporate Purposes | Statutory issue expenses & contingencies | Capped at 25% of gross issue proceeds under SEBI ICDR regulations |
6. Competitive Operational Strengths vs Critical Renewable Energy Risks
A rigorous equity assessment requires evaluating the operational competitive moats that differentiate Rayzon Solar alongside the global supply chain and technology risks inherent in solar manufacturing.
Competitive Operational Moats
- Proven High-Volume Manufacturing Scale: Operational track record delivering over 1.8 GW of module shipments in FY26, supported by highly automated, robotics-assisted cleanroom production lines.
- Integrated Technology Transition (TOPCon): Early strategic shift from legacy p-type Mono-PERC modules to high-efficiency n-type TOPCon bifacial modules providing higher wattage output and lower degradation rates.
- Strategic Geographical Hub: Located in Surat, Gujarat, close to Mundra and Hazira ports, ensuring freight advantages for incoming raw materials and international containerized exports.
- 100% Fresh Issue Alignment: The entire ₹1,500 Crore capital pool directly bolsters corporate equity and asset creation, aligning founding promoters with long-term capacity expansion.
Key Regulatory & Industry Risks
- Upstream Raw Material Dependency: Until the 3.5 GW cell line is fully commissioned, Rayzon remains dependent on imported solar cells and polysilicon wafers; global price spikes or shipping bottlenecks could affect short-term margins.
- Project Commissioning Delays: Construction and equipment installation for high-precision 3.5 GW cell lines carry execution risks; any delays in machinery imports or utility grid hookups could postpone expected output.
- Policy & Tariff Volatility: Shifts in Basic Customs Duty (BCD), ALMM implementation guidelines, or US import tariff regulations could alter competitive pricing dynamics against overseas module exporters.
- Rapid Technological Obsolescence: The solar PV industry experiences rapid technology cycles (such as heterojunction/HJT and perovskite tandem cells); staying competitive requires continuous R&D capex.
7. Intermediaries & Advisory Syndicate
The public offering is managed by a top-tier institutional syndicate:
- Book Running Lead Managers (BRLMs): D&A Financial Services, Nuvama Wealth Management, and Motilal Oswal Investment Banking are coordinating institutional roadshows, Anchor investor allocations, and regulatory book building.
- Registrar to the Issue: MUFG Intime India Private Limited (formerly Link Intime India Private Limited). MUFG Intime is responsible for bid collection, ASBA mandate reconciliations, computerized allotment algorithms, and electronic share credits.
8. Regulatory Timeline Corridor: What Investors Should Expect Next
With the submission of the DRHP Addendum on 17 September 2026, Rayzon Solar is entering the final preparatory phase of its public offering:
| Milestone | Current Status / Tentative Schedule | Statutory Requirement |
|---|---|---|
| DRHP Addendum Filing | Completed on 17 September 2026 | Recorded with SEBI & published on company IR portal |
| Final RHP Registration with RoC | Tentative (Following SEBI clearance) | Final prospectus incorporating price band corridor |
| Price Band & Lot Size Announcement | Minimum 2 working days prior to Issue Open | Nationwide statutory newspaper advertisements |
| Anchor Investor Allocation | 1 working day prior to Public Opening | Up to 60% of QIB quota allocated to institutional anchors |
| Public Bidding Window (UPI ASBA) | 3 working days | Retail, HNI, and institutional bidding open |
| Basis of Allotment Finalization | T+1 day following Issue Close | Computerized lottery allocation under SEBI supervision |
| Secondary Market Listing (BSE & NSE) | T+3 days following Issue Close | Trading debut at 10:00 AM under T+3 settlement mandate |
9. Grey Market Premium (GMP) Clarification: Inactive at Addendum Stage
Retail investors actively seek Grey Market Premium (GMP) indications whenever a prominent renewable energy IPO advances in the regulatory pipeline. It is essential to understand how grey market trading operates:
As of 19 September 2026, there is no active or verified Grey Market Premium for Rayzon Solar Limited.
The grey market is an unofficial, unregulated over-the-counter forward trading arrangement. Grey market dealers only initiate quotations once the company has completed its final Red Herring Prospectus (RHP) registration and officially declared its Price Band and Bidding Dates. Any claims of an active GMP at the preliminary Addendum stage are speculative and unverified. Prospective bidders should evaluate fundamental offer documents, balance sheets, and industrial execution capacity rather than relying on unofficial forward sentiments.
Prepare for Upcoming Renewable & Solar IPOs
Open a free Demat and trading account online in minutes to apply in forthcoming Mainboard public issues with instant 1-click UPI ASBA mandate approval and zero equity delivery brokerage.
10. Editorial Verdict & What Investors Should Watch Next
The submission of the DRHP Addendum by Rayzon Solar Limited on 17 September 2026 confirms that the company is actively fine-tuning its capital expenditure deployment as it moves toward public listing.
With a 7.21% national market share and an aggressive backward-integration roadmap into 3.5 GW of solar cells, Rayzon Solar is positioning itself alongside listed solar giants like Premier Energies and Waaree Energies.
In the coming weeks, market participants should closely monitor:
- RHP Registration & Price Band Corridor: The announced price band and asking valuation multiples (P/E and EV/EBITDA) relative to listed solar PV module manufacturers.
- Anchor Book Quality: Participation from marquee sovereign wealth funds, domestic mutual funds, and global clean energy institutional investors.
- Progress on Surat Cell Facility: Milestone updates on cleanroom commissioning and equipment delivery for the 3.5 GW TOPCon plant.
Statutory Regulatory Disclosures & Editorial Disclaimer
Digital Arthalaya (digitalarthalaya.in) is an independent financial education and market news portal. This article is published strictly for investor education and informational purposes based on public regulatory filings submitted to the Securities and Exchange Board of India (SEBI) on 17 September 2026. This content does not constitute investment advice, a financial recommendation, an underwriting solicitation, or an offer to buy or sell securities.
Filing an Addendum to a Draft Red Herring Prospectus (DRHP) does not guarantee that an initial public offering will receive final regulatory approval or ultimately launch. Grey Market Premiums (GMP) are unofficial, unregulated, and volatile indicators. Prospective investors must thoroughly read the final Red Herring Prospectus (RHP), review operational risk factors, and consult a SEBI-registered financial advisor before submitting bids in any public offering.
Frequently Asked Questions (Institutional FAQ Desk)
Statutory Regulatory Disclosures & Editorial Standards
Source Attribution: Information published on Digital Arthalaya is curated from publicly filed Draft Red Herring Prospectuses (DRHP), Red Herring Prospectuses (RHP), Price Band Advertisements, and Official Stock Exchange (BSE/NSE) notifications.
Non-Advisory Mandate & Risk Warning: Digital Arthalaya is strictly an independent financial education portal and is not a SEBI-registered investment advisor or stock broker. IPO bidding and equity trading involve market risk, including potential loss of principal. Readers must conduct their own independent due diligence and read all offer documents carefully before making investment commitments.