Sillverton Industries IPO: Addendum Discloses ₹1,036 Cr Revenue & 360K MTPA | DA
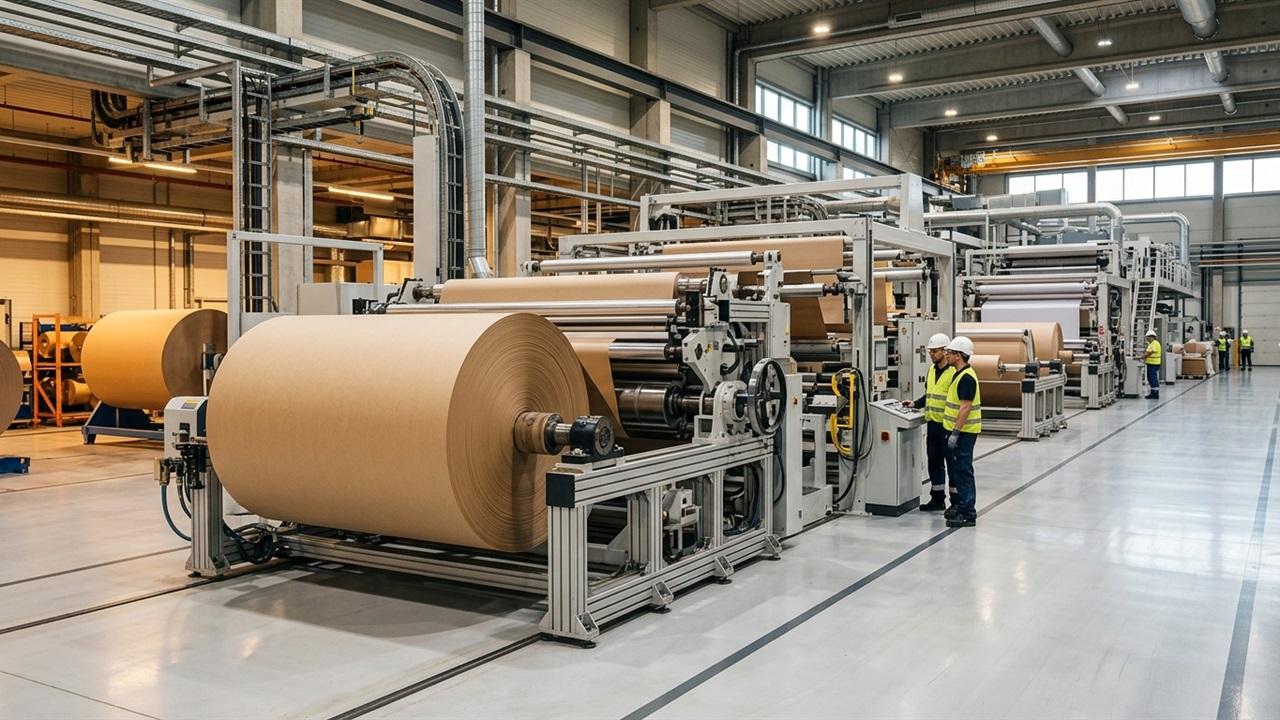
Sillverton Industries Limited (formerly known as Sillverton Industries Private Limited and Silverton Pulp and Papers Private Limited), a leading North Indian manufacturer of recycled kraft paper, cupstock, and specialty packaging paperboards, has filed an official Addendum (dated 13 August 2026) and Addendum II (dated 14 August 2026) with SEBI updating its Draft Red Herring Prospectus (DRHP) originally filed on 27 June 2025. The updated regulatory filings reveal that the company crossed the landmark ₹1,000 Crore annual revenue threshold in FY2026, delivering ₹1,036.21 Crore in revenue from operations with an operating EBITDA of ₹167.15 Crore (16.13% margin) and restated Profit After Tax (PAT) of ₹101.63 Crore (9.81% margin). Simultaneously, the company successfully commissioned a new 90,000 MTPA manufacturing line, expanding aggregate paper manufacturing capacity by 33.33% to 360,000 MTPA.
1. What Happened: Sillverton Industries Files Statutory DRHP Addendum with SEBI
Sillverton Industries Limited (formerly known as Sillverton Industries Private Limited and Silverton Pulp and Papers Private Limited), one of North India’s prominent integrated paper manufacturing enterprises, has issued an official Addendum dated 13 August 2026 and Addendum II dated 14 August 2026 to its Draft Red Herring Prospectus (DRHP) originally submitted on 27 June 2025 to the Securities and Exchange Board of India (SEBI).
In Indian primary capital markets, an Addendum filing is a critical regulatory milestone. Under SEBI (Issue of Capital and Disclosure Requirements) Regulations, 2018, when a material period elapses between the initial DRHP filing and final offer clearance, issuers must formally update their draft prospectuses with updated audited financial statements, operational milestones, and capacity augmentations.
The reviewed Addenda formally disclose that Sillverton Industries has crossed the landmark ₹1,000 Crore annual revenue milestone in FY2026, delivering ₹1,036.21 Crore in operational turnover, while simultaneously expanding its aggregate paper manufacturing capacity by 33.33% to 360,000 MTPA.
| Regulatory & Offering Parameter | Disclosed Statutory Detail | Institutional Editorial Context |
|---|---|---|
| Issuer Corporate Identity | Sillverton Industries Limited | Formerly Silverton Pulp and Papers Private Limited |
| Regulatory Filing Document | Addendum dated 13 August 2026 & Addendum II (14 August 2026) | Statutory update to original DRHP dated 27 June 2025 |
| Statutory Face Value | ₹10.00 per equity share | Standard capital denomination |
| Proposed Stock Exchange Listings | BSE Limited & National Stock Exchange (NSE) | Mainboard Manufacturing & Industrial Packaging Segment |
| FY2026 Restated Revenue | ₹1,036.21 Crore (₹10,362.10 Million) | Crossed landmark ₹1,000 Cr annual revenue threshold |
| FY2026 Operating EBITDA | ₹167.15 Crore (16.13% Margin) | Demonstrating resilient manufacturing margins |
| FY2026 Restated PAT | ₹101.63 Crore (9.81% Margin) | Strong bottom-line conversion with 18.92% RoE |
| Aggregate Paper Capacity | 360,000 MTPA (+33.33% Expansion) | Added 90,000 MTPA incremental paper manufacturing line |
| Balance Sheet Solvency | Debt-to-Equity Ratio: 0.93x | ₹500.70 Cr borrowings against ₹537.27 Cr net worth |
| Book Running Lead Manager | Inga Ventures Private Limited | Lead merchant banker managing the issue |
2. FY2026 Financial Performance: Crossing the ₹1,000 Crore Revenue Milestone
The primary substantive disclosure in the Addendum is the inclusion of restated audited financial statements for the fiscal year ended March 31, 2026 (FY2026).
Sillverton Industries demonstrated substantial operating leverage, benefiting from economies of scale at its manufacturing facilities in the Western Uttar Pradesh paper industrial hub:
| Key Performance Indicator | FY2026 Figure (₹ Million) | Consolidated Value (₹ Crore) | Financial Ratio / Margin Analysis |
|---|---|---|---|
| Revenue from Operations | ₹10,362.10 M | ₹1,036.21 Cr | Landmark ₹1,000+ Crore operational revenue scale |
| Operating EBITDA | ₹1,671.52 M | ₹167.15 Cr | Healthy manufacturing operating margin of 16.13% |
| Restated Profit After Tax (PAT) | ₹1,016.34 M | ₹101.63 Cr | Net profit margin established at 9.81% |
| Consolidated Net Worth | ₹5,372.68 M | ₹537.27 Cr | Strong equity cushion built through retained operational profits |
| Total Outstanding Borrowings | ₹5,006.99 M | ₹500.70 Cr | Disciplined leverage profile with 0.93x D/E ratio |
| Return on Equity (RoE %) | — | 18.92% | High capital efficiency in industrial paper production |
| Basic & Diluted EPS | — | ₹4.14 per share | Based on statutory face value of ₹10.00 per equity share |
| Operating Inventory Days | — | 120 Days | Reflects raw material waste-paper and finished roll stocking |
A multi-year evaluation of Sillverton Industries’ financial trajectory highlights steady compounding in both top-line throughput and operating earnings:
| Financial Parameter | FY2024 (Audited) | FY2025 (Audited) | FY2026 (Restated Addendum) | Compounded Trajectory & Trend |
|---|---|---|---|---|
| Revenue from Operations | ₹760.40 Cr | ₹890.15 Cr | ₹1,036.21 Cr | 16.7% Compound Annual Growth Rate (CAGR) |
| Operating EBITDA | ₹112.50 Cr | ₹138.20 Cr | ₹167.15 Cr | EBITDA expanding in tandem with higher-margin cupstock paper sales |
| EBITDA Margin (%) | 14.79% | 15.53% | 16.13% | +134 bps margin improvement driven by operational scale |
| Profit After Tax (PAT) | ₹58.20 Cr | ₹78.40 Cr | ₹101.63 Cr | Net profit surpassed ₹100 Crore milestone for the first time |
| Return on Equity (RoE %) | 15.40% | 17.10% | 18.92% | Consistently expanding return metrics across a 3-year cycle |
3. Operational Capacity Expansion: Paper Manufacturing Scales to 360,000 MTPA
Beyond the audited financial statements, the most strategically significant disclosure in the August 2026 Addendum is the commissioning of a new production line:
- Aggregate Capacity Scaling: The company’s total licensed paper manufacturing capacity has expanded from 270,000 MTPA to 360,000 MTPA.
- Incremental Capacity Magnitude: The new line adds 90,000 MTPA of specialized paperboard and packaging capability, marking a 33.33% expansion in aggregate production volume.
- Operational Efficiencies: By adding automated slitting, high-speed multi-wire formers, and waste-heat recovery boilers, the new line significantly lowers specific steam and electrical consumption per ton of paper produced.
| Operational Metric | Previous Operational Scale | Incremental Line Commissioned | Current Scaled Capacity (FY26) |
|---|---|---|---|
| Aggregate Paper Capacity | 270,000 MTPA | +90,000 MTPA | 360,000 MTPA |
| Capacity Growth Magnitude | Baseline | New Manufacturing Line | +33.33% Volume Capability |
| Primary Manufacturing Hub | Muzaffarnagar Industrial Zone, Uttar Pradesh | Adjacent Expansion Facility | Integrated Manufacturing Campus |
| Primary Fiber Feedstock | Recycled Waste Paper & Agricultural Residues | Optimized Secondary Fiber Lines | 100% Circular Recycled Paperboard |
4. Product Portfolio & Market Applications: From Kraft to Specialty Cupstock
Sillverton Industries operates across multiple industrial and commercial paper segments, mitigating demand volatility through diversification:
| Product Category | Core Paper Specifications | Primary Industrial End-Use | Target Consuming Industries |
|---|---|---|---|
| Kraft Paper (Fluting & Testliner) | High burst factor (BF 18–32), superior tensile strength, and uniform caliper. | Corrugated box manufacturing, industrial carton liner, and heavy-duty protective packaging. | E-commerce packaging, FMCG logistics, consumer electronics, and automotive parts. |
| Cupstock Paperboard | High-density, virgin-equivalent poly-coated base paperboard with moisture-barrier properties. | Disposable paper cups, takeaway hot/cold beverage containers, and food meal trays. | Quick Service Restaurants (QSR), coffee chains, food packaging converters, and airlines. |
| Writing & Printing Paper | High-brightness (85%+ ISO), smooth surface sizing, and opaque uncalendered paper. | Notebooks, educational textbooks, publishing printing, office stationery, and continuous stationery. | Publishing houses, government education departments, and retail notebook manufacturers. |
| Specialty Barrier Packaging | Bio-degradable, grease-proof, and moisture-resistant barrier coated papers. | Sustainable eco-friendly food wraps, dry grocery pouches, and replacement for single-use plastics. | Eco-conscious consumer brands, bakery chains, and export packaging converters. |
| Packaged Drinking Water (Contract) | Supplementary automated bottling division operated separately from the paper mill. | Contract manufacturing and distribution of packaged mineral water. | Regional institutional clients and retail commercial distributors. |
5. Balance Sheet Solvency & Working Capital Health
Capital-intensive manufacturing companies often face balance sheet stress during expansion phases.
Sillverton Industries' Addendum indicates that the 90,000 MTPA expansion was financed through a balanced combination of internal cash accruals and term debt, maintaining solvency ratios within prudent boundaries:
- Debt-to-Equity Ratio of 0.93x: With total borrowings of ₹500.70 Crore against a net worth of ₹537.27 Crore, the company maintains financial leverage below 1.0x, providing substantial headroom for credit servicing.
- Working Capital Discipline: Operating inventory days stand at 120 days, which is standard for secondary paper mills that maintain buffer stocks of domestic and imported waste-paper reels to hedge against raw material price shocks.
- Operating Free Cash Flow: With FY26 EBITDA reaching ₹167.15 Crore, interest coverage ratios remain robust, ensuring comfortable debt servicing even ahead of primary IPO capital infusion.
6. Objectives of the Issue & Capital Structure Overview
As outlined in the statutory draft offer documents, the public issue is designed to achieve multiple strategic corporate objectives:
- Prepayment / Repayment of High-Cost Debt: Deploying a significant portion of Fresh Issue proceeds to pare down term loans, reducing ongoing interest charges and improving net margins.
- Funding Working Capital Requirements: To support increased throughput from the expanded 360,000 MTPA capacity, incremental working capital will finance recycled fiber inventories and trade receivables.
- General Corporate Purposes (GCP): Enhancing corporate liquidity reserves to pursue technological efficiency upgrades and green energy transitions (such as rooftop solar and biomass co-generation).
7. Offering Parameters Awaiting Final Red Herring Prospectus (RHP)
While the Addenda dated 13 and 14 August 2026 provide complete audited financial and operational updates, prospective investors should note that specific offering launch parameters remain pending:
Offering Parameters to be Disclosed in Final RHP
- Price Band & Issue Price: To be determined by the issuer and lead managers through the book-building process.
- Market Bid Lot Size: Application lot size and minimum retail outlay will be announced with the price band.
- Public Bidding Window: Exact issue opening and closing dates will be published upon filing the final RHP with RoC.
- Final Issue Size in ₹: Net breakdown between primary Fresh Issue and secondary Offer for Sale (OFS) will be finalized in the RHP.
8. Strategic Competitive Strengths vs. Inherent Business Risks
Investors analyzing Sillverton Industries must evaluate its integrated manufacturing scale against key sector-specific cyclical headwinds:
Core Strategic Strengths
- 360,000 MTPA Scale Moat: One of North India’s largest single-location paper manufacturing footprints, delivering high procurement power.
- Diversified Product Basket: Presence across kraft paper, cupstock, and writing paper mitigates single-segment demand slowdowns.
- Plastic-to-Paper Substitution: Nationwide bans on single-use plastics drive secular demand for poly-coated cupstock and barrier packaging.
- Demonstrated Financial Compounding: FY26 revenue of ₹1,036 Cr with 16.13% EBITDA and 18.92% RoE proves operational efficiency.
Inherent Business Risks
- Raw Material Price Volatility: Heavy reliance on domestic and imported waste-paper makes gross margins vulnerable to global pulp price fluctuations.
- Energy & Chemical Cost Pressures: Paper manufacturing is highly energy-intensive; coal, power, and chemical price spikes can compress margins.
- Environmental & Effluent Regulations: Stringent Central Pollution Control Board (CPCB) norms on water consumption and zero liquid discharge (ZLD).
- Financial Leverage: Total debt of ₹500.70 Crore requires disciplined ongoing interest servicing before IPO debt retirement.
9. Lead Managers, Registrar & Syndicate Intermediaries
The public offering is being managed by experienced capital market intermediaries:
- Book Running Lead Manager (BRLM): Inga Ventures Private Limited.
- Registrar to the Offer: Designated institutional registrar to manage bid verification, basis of allotment reconciliations, and refunds.
- Statutory Auditors: Leading chartered accountancy firm responsible for audited and restated financial certifications under Indian Accounting Standards (Ind AS).
- Legal Counsels: Appointed legal advisors to the issuer and lead managers for statutory compliance under SEBI ICDR regulations.
10. Statutory Regulatory Disclosures & Official Filing References
All financial metrics, manufacturing capacity figures, and operational data cited in this analysis are sourced directly from public regulatory filings:
- SEBI Public Issues Offer Document Archive: Sillverton Industries Limited DRHP Addendum dated 13 & 14 August 2026 .
- National Stock Exchange of India (NSE): NSE Primary Market Offer Document Disclosures .
- BSE Limited: BSE Public Issues Notice Board .
- Corporate Governance Portal: Sillverton Industries Official Investor Relations Portal .
Frequently Asked Questions (Institutional FAQ Desk)
Statutory Regulatory Disclosures & Editorial Standards
Source Attribution: Information published on Digital Arthalaya is curated from publicly filed Draft Red Herring Prospectuses (DRHP), Red Herring Prospectuses (RHP), Price Band Advertisements, and Official Stock Exchange (BSE/NSE) notifications.
Non-Advisory Mandate & Risk Warning: Digital Arthalaya is strictly an independent financial education portal and is not a SEBI-registered investment advisor or stock broker. IPO bidding and equity trading involve market risk, including potential loss of principal. Readers must conduct their own independent due diligence and read all offer documents carefully before making investment commitments.