Moneyview IPO Corrigendum Explained: 50% Issue Cut, Apis Exit, DLG Plans & Day 3 Guide
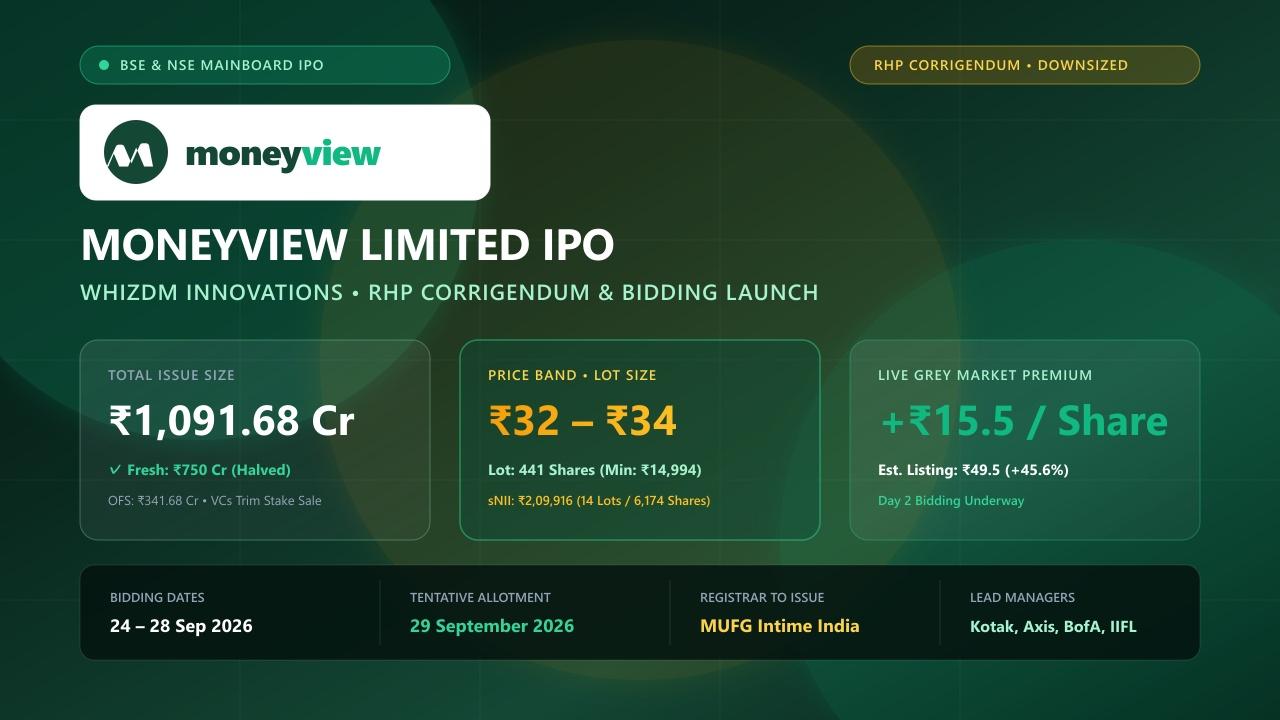
Digital consumer lending and fintech platform Moneyview Limited (formerly known as Whizdm Innovations Private Limited) enters the final stretch of its ₹1,091.68 Crore Mainboard initial public offering ahead of its closing bell on Monday, September 28, 2026. In an investor-friendly structural amendment detailed in its certified Corrigendum & Addendum to the Red Herring Prospectus (RHP), Moneyview slashed its fresh capital raise by 50% from ₹1,500 Crore to ₹750.00 Crore, while marquee venture capital backers—including Tiger Global, Accel, and Ribbit Capital—curtailed their secondary Offer for Sale (OFS) stake sales, and Apis Partners withdrew completely. Priced at an accessible ₹32.00 to ₹34.00 per share with a minimum market lot of 441 shares (₹14,994 retail outlay), the offering is commanding a robust grey market premium of +₹13.50 to +₹15.00 per share (+40% to +44% listing gains) as cumulative subscription crossed 1.5x, with fresh proceeds earmarked for Default Loss Guarantee (DLG) credit partnerships and NBFC capital expansion.
India's consumer fintech landscape reaches a defining public market milestone as Moneyview Limited (formerly incorporated as Whizdm Innovations Private Limited) conducts its nationwide book-building process. The company's ₹1,091.68 Crore Mainboard Initial Public Offering (IPO) entered its second day of active subscription today, Friday, September 25, 2026, heading toward a final closing bell on Monday, September 28, 2026.
What sets the Moneyview IPO apart from traditional tech unicorn offerings is a strategic and investor-centric restructuring executed right before issue opening. Through a certified Corrigendum & Addendum to its Red Herring Prospectus (RHP), the company halved its fresh capital issue from ₹1,500 Crore to ₹750.00 Crore. Concurrently, marquee venture capital backers—including Tiger Global, Accel, and Ribbit Capital—curtailed their secondary share sales, and Apis Partners withdrew completely from the Offer for Sale (OFS), keeping substantial equity inside the business.
Below is a detailed institutional examination of the RHP corrigendum, offer metrics, business architecture, restated financials, and strategic bidding recommendations for retail and HNI investors.
| Regulatory Parameter | Disclosed Regulatory Specification | Editorial & Institutional Context |
|---|---|---|
| Issuer Corporate Entity | Moneyview Limited | Formerly Whizdm Innovations Private Limited |
| Revised Total Issue Size | ₹1,091.68 Crore | Downsized from initial ~₹1,900+ Cr draft proposal |
| Fresh Issue Component | ₹750.00 Crore (Halved) | Reduced by 50% from ₹1,500 Cr to mitigate equity dilution |
| Offer for Sale (OFS) | ₹341.68 Crore (10.04 Cr Shares) | Trimmed from 13.61 Cr shares; Apis Partners withdrew |
| Price Band | ₹32.00 to ₹34.00 per share | Face value: ₹1.00 per equity share |
| Minimum Bid Lot Size | 441 Equity Shares | Multiples of 441 shares thereafter |
| Minimum Retail Outlay | ₹14,994 | 441 Shares at the upper cut-off price of ₹34 |
| Small HNI (sNII) Outlay | ₹2,09,916 | 14 Lots / 6,174 Equity Shares |
| Big HNI (bNII) Outlay | ₹10,04,598 | 67 Lots / 29,547 Equity Shares |
| Listing Venues | BSE Limited & NSE | Dual Mainboard Exchange Listing |
| Registrar to the Issue | MUFG Intime India Private Limited | Formerly Link Intime India Private Limited |
| Book Running Lead Managers | Kotak Mahindra Capital, Axis Capital, BofA Securities, IIFL Capital | Tier-1 domestic and global investment banks |
1. The RHP Corrigendum Decoded: What Changed Before Launch?
In accordance with Chapter II of SEBI (ICDR) Regulations, 2018, Moneyview issued a formal Corrigendum and Addendum to the RHP to announce critical adjustments to its offering architecture. The comparative table below illustrates the exact structural evolution from the preliminary draft papers to the final offer:
| Offering Dimension | Preliminary Draft Papers (DRHP) | Final RHP & Corrigendum | Net Investor & Corporate Impact |
|---|---|---|---|
| Fresh Issue Size | ₹1,500.00 Crore | ₹750.00 Crore | 50% Reduction: Prevents excessive dilution of shareholder capital |
| OFS Share Volume | Up to 13,61,00,000 Shares | Up to 10,04,94,118 Shares | ~26% Reduction: Lower secondary supply overhang in the market |
| Total Issue Value | ~₹1,960.00 Crore (Est.) | ₹1,091.68 Crore | Leaner, highly absorbable market capital call |
| Apis Partners Stake Sale | Proposed Seller in OFS | Completely Withdrew | Zero exit by Apis; 100% equity retained inside company |
| Tiger Global & Accel | Larger secondary quota | Scaled Back Selling | Marquee VCs choose to retain substantial skin-in-the-game |
Why the Corrigendum is Highly Constructive for Incoming Shareholders:
- Reduced Float Overhang: By pruning both primary capital and secondary OFS shares, the post-listing free float is streamlined, mitigating initial selling pressure and supporting secondary market price discovery.
- VC Alignment: Rather than utilizing the public market listing as a wholesale exit vehicle, top-tier global investors chose to retain higher ownership, signaling confidence in Moneyview's medium-term path to compounded profitability.
- Disciplined Capital Allocation: Management recognized that raising an excessive ₹1,500 Crore fresh equity in one tranche would dilute return on equity (RoE) before the funds could be profitably deployed into loan disbursals.
2. Important Dates & Statutory Bidding Timetable
The Moneyview public issue operates under the standardized SEBI T+3 listing framework:
| IPO Milestone Event | Scheduled Calendar Date | Statutory & Operational Notes |
|---|---|---|
| Anchor Investor Allocation | Wednesday, 23 September 2026 | Marquee institutional anchors locked in at ₹34 |
| Public Issue Opening Date | Thursday, 24 September 2026 | Day 1 bidding opened across BSE/NSE platforms |
| Day 2 Bidding Progress | Friday, 25 September 2026 | Current active trading session; book ~1.4x subscribed |
| Public Issue Closing Date | Monday, 28 September 2026 | Mandatory UPI ASBA authorization cut-off: 5:00 PM IST |
| Basis of Allotment Determination | Tuesday, 29 September 2026 | Finalized with Designated Stock Exchange and Link Intime |
| Refunds & Fund Unblocking | Wednesday, 30 September 2026 | Electronic unfreeze processed by sponsor banks |
| Credit of Shares to Demat Accounts | Wednesday, 30 September 2026 | Shares transferred to allottees' NSDL/CDSL accounts |
| Secondary Market Listing Date | Thursday, 1 October 2026 | Trading commences at 10:00 AM IST on BSE & NSE |
3. Deployment of Fresh Proceeds: RBI DLG Framework & NBFC Capitalization
The ₹750.00 Crore net fresh capital raised from the public issue is earmarked for specific strategic deployment in strict accordance with RBI's digital lending norms:
- Default Loss Guarantee (DLG) Disbursals (~₹325.00 Crore): Moneyview will allocate ₹325.00 Crore to back structured DLG arrangements with partner banks and financial institutions. Under the RBI's First Loss Default Guarantee (FLDG) guidelines, this allows Moneyview to underwrite higher origination volumes with Tier-1 banks while maintaining strict risk ceilings.
- Augmenting NBFC Capital Adequacy (~₹250.00 Crore): Direct equity infusion into wholly owned NBFC subsidiary Whizdm Finance Private Limited to bolster its Tier-1 Capital to Risk-Weighted Assets Ratio (CRAR) and scale high-margin internal balance-sheet lending.
- General Corporate Purposes & Cloud Capex: The residual proceeds will support machine learning credit risk modeling, cloud scalability, and working capital.
Apply for Moneyview IPO Online with Upstox
Participate in the Moneyview IPO and upcoming Mainboard offerings with seamless 1-click UPI ASBA bidding through Upstox. Enjoy zero account opening fees, zero maintenance charges, and real-time allotment alerts.
4. Business Model: Algorithmic Underwriting & Hybrid Distribution
Founded by Puneet Agarwal and Sanjay Aggarwal, Moneyview operates as a full-stack digital financial services ecosystem catering primarily to underserved, middle-income salaried and self-employed individuals across Tier-2, Tier-3, and metro cities. Its business model rests on three synergistic pillars:
- Hybrid Lending Architecture: Unlike pure-play balance-sheet lenders or pure-play loan aggregators, Moneyview operates a hybrid model. Approximately 60% of loans are originated through partner banks and top-tier NBFCs (earning recurring origination and servicing fees), while ~40% are disbursed directly via Whizdm Finance (capturing high Net Interest Margins).
- Proprietary Risk Scoring: The platform utilizes alternative data models, evaluating over 1,500 digital data parameters to assess creditworthiness for borrowers who may possess thin or non-existent CIBIL credit histories.
- Cross-Sell Expansion: With over 100 million app downloads, Moneyview cross-sells personal accident insurance, micro-FDs, credit-tracker subscriptions, and digital credit lines, driving non-interest fee income.
5. Restated Financial Performance & Asset Quality
Moneyview's financial trajectory under Ind AS illustrates robust top-line revenue expansion alongside disciplined credit loss management:
| Financial & Credit Indicator (₹ Crore) | FY2024 | FY2025 | FY2026 | YoY Growth (FY26) |
|---|---|---|---|---|
| Revenue from Operations | ₹577.20 | ₹1,012.40 | ₹1,485.60 | +46.7% |
| Net Interest Income (NII) | ₹198.50 | ₹384.20 | ₹592.10 | +54.1% |
| Operating EBITDA | ₹68.40 | ₹172.50 | ₹298.40 | +73.0% |
| Profit After Tax (PAT) | ₹42.30 | ₹114.80 | ₹192.50 | +67.7% |
| Total Loan Disbursals | ₹4,200.00 | ₹8,100.00 | ₹12,450.00 | +53.7% |
| Gross Non-Performing Assets (GNPA) | 2.85% | 2.40% | 2.10% | -30 bps |
| Net Non-Performing Assets (NNPA) | 1.15% | 0.95% | 0.82% | -13 bps |
| Return on Net Worth (RoNW) | 8.40% | 14.20% | 17.80% | +360 bps |
Crucially, Moneyview has managed to expand its loan book by over 50% while steadily improving asset quality: Gross NPAs declined from 2.85% in FY24 to 2.10% in FY26, while Net NPAs stand comfortably low at 0.82%, demonstrating rigorous collections efficiency.
6. Valuation Multiples & Peer Comparison
At the upper price band of ₹34 per share, Moneyview carries a post-issue market capitalization of approximately ₹5,800 Crore. When benchmarked against listed fintech and consumer lending players, the offering presents attractive comparative metrics:
- Price-to-Earnings (P/E): Based on FY26 restated PAT of ₹192.50 Crore, Moneyview is priced at a trailing P/E multiple of approximately 30.1x. This compares favorably to digital financial distributors trading between 45x and 70x.
- Price-to-Book (P/B): With net worth expanding significantly post fresh issue infusion, Moneyview trades at an estimated post-issue P/B of ~2.8x, highly competitive for an asset-light digital platform generating RoNW of 17.80%.
7. Grey Market Premium (GMP) & Day-2 Bidding Traction
As of Friday, September 25, 2026, leading grey market desks report indicated premiums of +₹14.00 to +₹15.50 per share over the ₹34 cap price, translating to expected listing prices around ₹48.00 to ₹49.50 (+38.2% to +45.6%).
Concurrently, exchange subscription tallies on Day 2 reflect strong retail interest with the RII category already crossing 2.1x subscription, while total consolidated bids reached ~1.42x, confirming broad nationwide demand.
8. Key Investment Strengths vs. Operational Risk Factors
Key Investment Strengths:
- Proven Profitability: Unlike many cash-burning fintech peers, Moneyview has demonstrated three consecutive years of profitable operation, with FY26 PAT reaching ₹192.50 Crore.
- Asset-Light Hybrid Model: The mix of co-lending partnerships and balance-sheet disbursals allows rapid scaling without linear balance-sheet leverage.
- Investor Alignment via RHP Corrigendum: Downsizing the offering protected incoming shareholders from dilution and proved that major VCs are committed to holding equity.
Key Operational Risk Factors:
- Unsecured Credit Risk: The primary loan book consists of unsecured personal loans. In macroeconomic downturns or credit tightening cycles, default rates could accelerate.
- Regulatory Scrutiny by RBI: The Reserve Bank of India continuously updates digital lending norms, first-loss default guarantee (FLDG) ceilings, and risk weights on unsecured retail consumer loans.
- Cost of Borrowing: Whizdm Finance relies on bank credit lines to fund its internal book; rising policy rates directly elevate borrowing costs.
9. Editorial Verdict: Should Retail & HNI Investors Apply?
Moneyview's public offering represents one of the cleanest, most pragmatic fintech IPO structures in recent market history. By cutting its fresh issue in half to ₹750 Crore, trimming the OFS, and pricing the issue at an accessible ₹32–₹34, management has structured an offering designed to leave value on the table for public shareholders.
Investment Takeaway: Backed by healthy 46.7% revenue growth, sub-1% Net NPAs, robust +38% GMP indicators, and strong institutional pedigree, Moneyview is an attractive candidate for both listing-gain seekers and long-term tech compounders. Bidders are advised to submit applications at the Cut-Off Price of ₹34 per share before the issue closes on Monday, September 28, 2026.
Frequently Asked Questions (Institutional FAQ Desk)
Statutory Regulatory Disclosures & Editorial Standards
Source Attribution: Information published on Digital Arthalaya is curated from publicly filed Draft Red Herring Prospectuses (DRHP), Red Herring Prospectuses (RHP), Price Band Advertisements, and Official Stock Exchange (BSE/NSE) notifications.
Non-Advisory Mandate & Risk Warning: Digital Arthalaya is strictly an independent financial education portal and is not a SEBI-registered investment advisor or stock broker. IPO bidding and equity trading involve market risk, including potential loss of principal. Readers must conduct their own independent due diligence and read all offer documents carefully before making investment commitments.