SIP & Power of Compounding: Mathematics, Rules & Step-Up (2026) | Digital Arthalaya
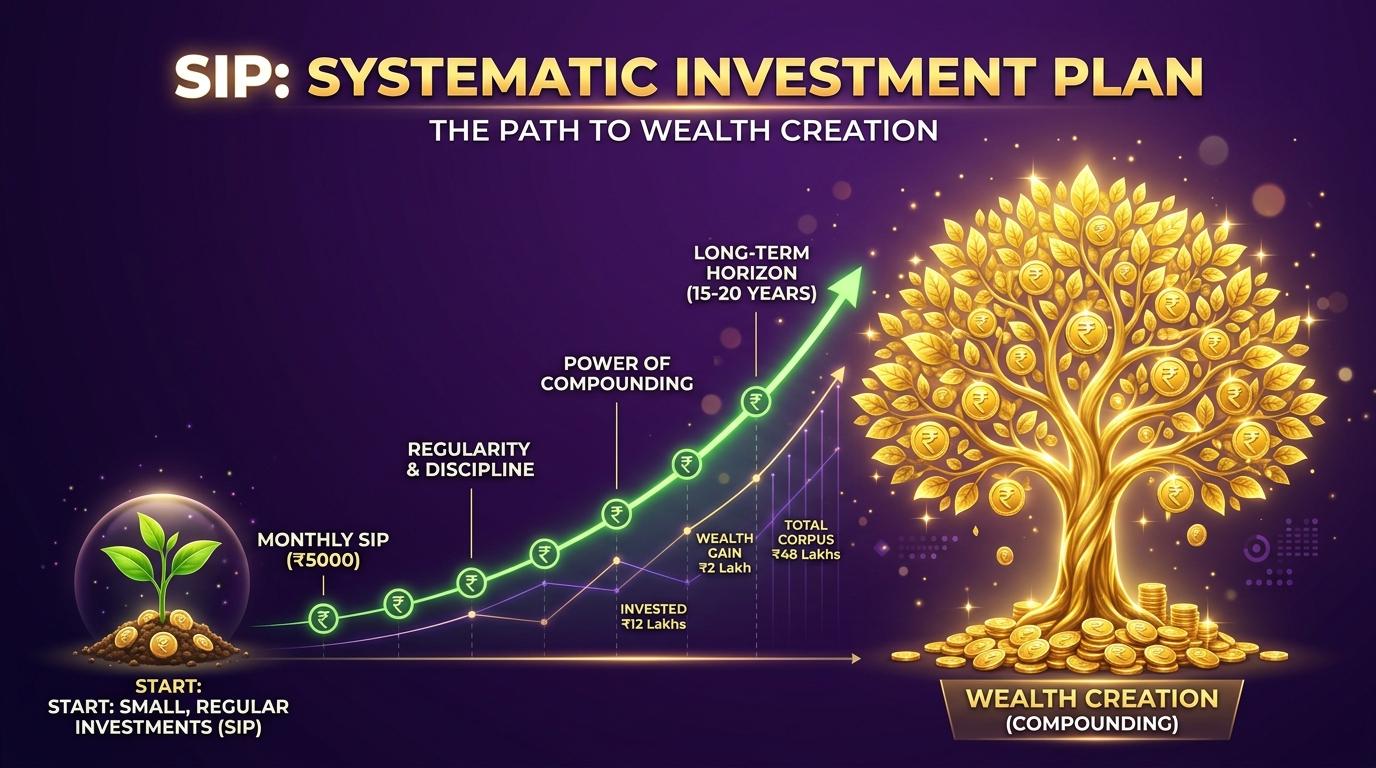
A Systematic Investment Plan (SIP) is an automated wealth-building mechanism that harnesses Rupee Cost Averaging and compound interest to build long-term capital. Key compounding dynamics: The compound interest formula makes time an exponential multiplier rather than invested capital; delaying an equity SIP by just 5 years can erode over 40% to 50% of the final retirement corpus. A 10% annual Step-Up SIP more than doubles the final 20-year wealth compared to a flat SIP. In addition, investing in Direct Plans rather than Regular Plans saves 0.5% to 1.2% in distributor trail commissions, compounding into a 20% to 25% larger terminal portfolio.
In the modern Indian financial ecosystem, the Systematic Investment Plan (SIP) has emerged as the single most transformative wealth-creation instrument for retail investors. According to official disclosures by the Association of Mutual Funds in India (AMFI), monthly gross SIP inflows across domestic mutual funds have surpassed ₹23,000+ Crore, driven by over 9.5 Crore active retail SIP folios. From young technology professionals in Bengaluru and Pune to salaried families across Tier-2 and Tier-3 towns, systematic equity investing is replacing traditional physical savings assets like fixed deposits, physical gold, and real estate as the primary engine of household capital accumulation.
However, while millions of Indians commit capital to mutual fund SIPs each month, few fully grasp the underlying mathematical forces that govern compound interest, the structural advantages of Rupee Cost Averaging (RCA), the severe terminal wealth penalty imposed by the "Cost of Delay," or the compounding drag of distributor commissions in Regular mutual fund plans. Furthermore, following the landmark capital gains taxation restructuring under the Finance Act, 2024, investors must master the statutory First-In, First-Out (FIFO) redemption rules to protect their hard-earned wealth. This comprehensive 2026 institutional guide provides an exhaustive breakdown of SIP wealth architecture, compounding mathematics, Step-Up strategies, and portfolio construction.
1. Understanding Systematic Investment Plans (SIP): Core Concept & Mechanics
A Systematic Investment Plan is not an asset class or an independent financial product; rather, it is a disciplined, automated method of investing a fixed sum of money at predetermined calendar intervals (typically monthly, weekly, or quarterly) into a chosen open-ended mutual fund scheme. Regulated under the statutory framework of the Securities and Exchange Board of India (Mutual Funds) Regulations, 1996, an SIP eliminates the emotional burden and behavioral errors associated with trying to "time" volatile equity markets.
How the SIP Execution Pipeline Works
1. Automated Banking Mandate: The investor registers an electronic mandate via UPI AutoPay or an e-NACH / One-Time Mandate (OTM) through the National Payments Corporation of India (NPCI) network. This authorizes the mutual fund's banking gateway to debit a fixed amount (e.g., ₹5,000) on a chosen calendar date each month.
2. Net Asset Value (NAV) Allotment: The debited funds are transferred to the mutual fund scheme's custodial account. Based on SEBI's official cut-off timing rules (3:00 PM IST for equity schemes), the Asset Management Company (AMC) allots mutual fund units based on the official closing Net Asset Value (NAV) of that business day.
3. Continuous Unit Accumulation: The allotted units are credited to the investor's mutual fund folio (accessible via Statement of Account - SoA or electronic Demat custody), incrementally compounding total folio units month after month.
SIP vs. Lumpsum: When Does Each Strategy Win?
Investors frequently debate whether deploying capital via SIP or Lumpsum is mathematically superior:
- Lumpsum Outperforms in One-Way Secular Bull Markets: When equity markets experience an uninterrupted, continuous upward trend, deploying a large lump sum upfront produces higher returns because 100% of the capital is exposed to compounding immediately from Day 1.
- SIP Outperforms in Volatile, Sideways, or Corrective Markets: In realistic market conditions characterized by cycles, sharp corrections, and extended consolidations, SIP substantially outperforms lump-sum investments by automatically buying more units during market declines, dampening portfolio volatility and lowering the average acquisition cost.
2. The Mathematics of Compounding: Why Time Outweighs Capital
The core engine powering an SIP is compound interest—the mathematical phenomenon where the returns earned on an investment begin earning their own returns. In standard annual compound growth, the future value of an SIP is governed by the future value of an annuity formula:
Future Value of SIP (A) = P × [ ( (1 + r)^n - 1 ) / r ] × (1 + r)
Where P is the monthly installment, r is the periodic monthly interest rate (Annual Return / 12), and n is the total number of monthly installments.
The mathematical significance of this formula lies in the exponent n. While increasing the monthly investment amount P scales the final corpus linearly, increasing the time horizon n scales the final wealth exponentially. This dynamic creates the famous compounding "hockey stick" curve, which progresses across three distinct psychological phases:
- Years 1 to 5 (The Foundation Phase): During the initial 5 years, compounding appears disappointingly sluggish. Your total portfolio value is overwhelmingly dominated by your own out-of-pocket principal contributions (typically 75% to 85% of the total value), while compound returns account for only a modest slice. Many impatient investors mistakenly abandon their SIPs during this phase.
- Years 6 to 12 (The Momentum Phase): Compound returns begin matching and eventually exceeding your annual principal deposits. The portfolio develops gravitational pull; market gains generated in a single good year can exceed several years of cumulative monthly deposits.
- Years 13 to 20+ (The Wealth Explosion Phase): The compounding curve goes nearly vertical. Your original principal represents less than 20% of your total net worth, while compound returns generate over 80% of the corpus. An annual 12% return on a ₹1 Crore accumulated corpus adds ₹12 Lakh in wealth each year—far exceeding the annual salary savings of most investors!
The Rule of 72: Quick Doubling Estimator
The Rule of 72 is an invaluable mental math tool for long-term investors. By dividing 72 by the expected annual Compound Annual Growth Rate (CAGR), you can calculate approximately how many years it takes for your invested wealth to double:
- At 12% CAGR (Historical long-term return of NIFTY 50 / broad market index): $72 / 12 =$ 6 Years to double.
- At 14% CAGR (Actively managed flexi-cap or mid-cap portfolio): $72 / 14 =$ 5.1 Years to double.
- At 15% CAGR (High-growth small/mid-cap strategy): $72 / 15 =$ 4.8 Years to double.
3. Rupee Cost Averaging (RCA): Why Volatility is an SIP Investor's Ally
For the unhedged equity trader, market crashes are terrifying events that inflict emotional trauma. For the disciplined SIP investor, however, a market crash is the greatest wealth-multiplying blessing that Dalal Street can offer. This counter-intuitive reality is driven by Rupee Cost Averaging (RCA).
The Mechanics of Rupee Cost Averaging
Because an SIP commits a fixed rupee amount rather than purchasing a fixed quantity of units, the system operates on mathematical autopilot:
• When equity markets rally and NAVs are high, your fixed monthly allocation automatically purchases fewer units.
• When equity markets experience sharp corrections, bear markets, or global panics and NAVs plunge, your fixed monthly allocation automatically purchases a substantially larger number of units.
Practical Numerical Demonstration: Suppose you invest ₹10,000 monthly in an equity fund:
- Month 1 (Market Euphoria): NAV is ₹100. Your ₹10,000 buys 100 units.
- Month 2 (Market Crash - 20% Drop): NAV falls to ₹80. Your ₹10,000 buys 125 units.
- Month 3 (Panic Bottom - 50% Drop): NAV falls to ₹50. Your ₹10,000 buys 200 units.
- Month 4 (Partial Recovery): NAV rebounds to ₹80. Your ₹10,000 buys 125 units.
Total Capital Invested: ₹40,000. Total Units Accumulated: 550 units. Average purchase cost per unit: ₹72.72!
Notice that while the market has not even recovered to its original peak of ₹100 (it is currently trading at ₹80), the current portfolio value is $550 \times ₹80 =$ ₹44,000—generating an instant profit of +10% even though the market is still down 20% from its starting point! This is the magic of Rupee Cost Averaging: it forces investors to buy aggressively at bottoms and buy conservatively at peaks without making emotional forecasts.
4. The Brutal Cost of Delay: Why Starting 5 Years Early Changes Everything
In the realm of exponential compounding, time is infinitely more valuable than capital. Waiting for a "promotion," delaying investments until all lifestyle expenses are met, or postponing an SIP by just five years inflicts irreversible financial damage on your terminal wealth.
| Investor Profile | Starting Age | Investment Horizon (Till Age 60) | Monthly SIP Amount | Total Capital Invested | Corpus at Age 60 (12% CAGR) | Cost of Delay (Lost Wealth) |
|---|---|---|---|---|---|---|
| Early Starter (Aman) | Age 25 | 35 Years | ₹10,000 / month | ₹42.0 Lakh | ₹6.49 Crore | Baseline |
| Delayed Starter (Rohan) | Age 30 | 30 Years | ₹10,000 / month | ₹36.0 Lakh | ₹3.53 Crore | -₹2.96 Crore (-45.6%) |
| Late Starter (Vikram) | Age 35 | 25 Years | ₹10,000 / month | ₹30.0 Lakh | ₹1.89 Crore | -₹4.60 Crore (-70.8%) |
The Shocking Takeaway: Rohan delayed starting his SIP by just 5 years compared to Aman. Rohan saved ₹6.0 Lakh in out-of-pocket contributions by waiting, but sacrificed an astounding ₹2.96 Crore in lost terminal compounding wealth! Delaying by 10 years cost Vikram over ₹4.60 Crore. The lesson is unequivocal: starting with ₹1,000 or ₹2,000 today is vastly superior to waiting five years to start with ₹10,000.
5. The Power of Step-Up (Top-Up) SIP: The Wealth Multiplier
A standard flat SIP keeps your monthly investment constant across decades. However, an investor's personal income is rarely static; salaries, business profits, and annual increments steadily rise year after year. A Step-Up SIP (Top-Up SIP) is an automated facility that instructs the mutual fund to increase your monthly SIP contribution by a predetermined percentage (e.g., 10%) or a fixed rupee amount (e.g., ₹1,000) once every 12 months.
By synchronizing your investment rate with salary increments and inflation, a Step-Up SIP transforms your wealth accumulation curve:
| Investment Horizon | Flat SIP (₹10k/mo) Outlay | Flat SIP Value (12% CAGR) | 10% Step-Up SIP Outlay | 10% Step-Up Value (12% CAGR) | Extra Wealth Created by Step-Up |
|---|---|---|---|---|---|
| 10 Years | ₹12.0 Lakh | ₹23.2 Lakh | ₹19.1 Lakh | ₹34.1 Lakh | +₹10.9 Lakh (+47%) |
| 15 Years | ₹18.0 Lakh | ₹50.4 Lakh | ₹38.1 Lakh | ₹88.7 Lakh | +₹38.3 Lakh (+76%) |
| 20 Years | ₹24.0 Lakh | ₹99.9 Lakh (~₹1.0 Cr) | ₹68.7 Lakh | ₹2.16 Crore | +₹1.16 Crore (+116%) |
| 25 Years | ₹30.0 Lakh | ₹1.89 Crore | ₹1.18 Crore | ₹5.02 Crore | +₹3.13 Crore (+165%) |
Over a 20-year horizon, adopting a modest 10% annual Step-Up elevates your final portfolio from ₹1.0 Crore to over ₹2.16 Crore—more than doubling your total wealth with manageable, gradual increments.
6. Direct Plans vs. Regular Plans: The Silent Compounding Killer
In January 2013, SEBI introduced a landmark reform mandating that every mutual fund scheme must offer two distinct plan variants: a Direct Plan and a Regular Plan. Both plans hold the identical underlying portfolio of stocks, are managed by the exact same fund manager, and follow identical investment mandates. However, their cost structures differ dramatically:
| Plan Parameter | Direct Mutual Fund Plan | Regular Mutual Fund Plan |
|---|---|---|
| Distributor Trail Commission | Zero (0%) Commission | 0.5% to 1.5% per annum paid to agent/bank |
| Total Expense Ratio (TER) | Significantly Lower (e.g. 0.40% to 0.80%) | Higher (e.g. 1.20% to 2.10%) |
| Net Asset Value (NAV) | Higher NAV (because fewer expenses deducted) | Lower NAV |
| 25-Year Impact on ₹10k SIP | ₹1.89 Crore (assuming 12% CAGR) | ₹1.51 Crore (assuming 11% net CAGR) |
| Terminal Compounding Difference | You lose approximately ₹38 Lakhs (over 20% of your wealth) in distributor trail commissions! | |
To avoid this compounding drag, modern self-directed investors should execute mutual fund SIPs exclusively in Direct-Growth Plans using platforms like MF Central (the official registrar platform backed by CAMS and KFintech), AMC websites, or registered discount brokers.
7. Mutual Fund SIP Taxation: The Critical FIFO Rule & Capital Gains
Investing in equity mutual funds triggers capital gains taxation only upon redemption (selling) of units. Under the restructured tax regime enacted via the Finance Act, 2024 (effective July 23, 2024), equity-oriented mutual fund taxation is structured as follows:
Post-Budget 2024 Mutual Fund Tax Architecture
1. Short-Term Capital Gains (STCG) [Section 111A]: Units held for 12 months or less are taxed at 20% flat (increased from 15%), plus applicable surcharge and 4% health & education cess.
2. Long-Term Capital Gains (LTCG) [Section 112A]: Units held for more than 12 months are taxed at 12.5% (increased from 10%) on cumulative gains exceeding the enhanced statutory exemption of ₹1.25 Lakh per financial year (increased from ₹1.0 Lakh).
The First-In, First-Out (FIFO) Rule for Ongoing SIPs
A critical tax trap for SIP investors is the First-In, First-Out (FIFO) principle mandated by Section 45(2A) of the Income-tax Act. An SIP is not a single monolith investment; every single monthly installment represents an independent investment with its own distinct 12-month clock.
Example: If you have run an SIP for 24 months and decide to redeem 50% of your portfolio today, the tax department assumes that the units being sold are the oldest units bought in Months 1 through 12. Those units qualify as Long-Term Capital Gains (12.5% tax above ₹1.25L). However, if you redeem your entire portfolio including units bought 3 or 6 months ago, those recent units will be classified as Short-Term Capital Gains and hit with a 20% STCG tax!
Systematic Withdrawal Plans (SWP): The Tax-Efficient Retirement Cash Flow
When entering retirement, investors should avoid choosing the IDCW (Income Distribution cum Capital Withdrawal / Dividend) option, as dividends are taxed at your marginal personal income tax slab rate (up to 39%). Instead, modern retirees utilize a Systematic Withdrawal Plan (SWP) from the Growth option: only the capital gains component of each monthly withdrawal is taxed under Section 112A (12.5%), creating a highly tax-efficient monthly income stream.
8. Strategic Best Practices: Dates, Frequencies, and Category Allocation
To maximize compounding efficiency, retail investors should align their SIPs with these empirical best practices:
A. The Myth of the "Best SIP Date"
Financial media frequently speculates whether running an SIP on the 1st, 10th, 15th, or 25th of the month yields superior returns. Long-term backtesting across 15+ years of NIFTY 50 and S&P BSE SENSEX data demonstrates conclusively that the return difference between different dates of the month is less than 0.1% CAGR. The mathematically optimal date to set your SIP is simply 2 to 3 days after your monthly salary is credited (e.g., the 5th or 7th), ensuring disciplined savings before discretionary spending occurs.
B. Daily vs. Weekly vs. Monthly SIP Frequency
While mutual funds allow Daily, Weekly, and Monthly SIP frequencies, academic studies reveal that Daily or Weekly SIPs do not generate meaningfully higher returns than Monthly SIPs over 5+ years. In fact, Daily SIPs generate hundreds of micro-transactions that clutter your bank statement and create unnecessary bookkeeping friction during tax filing. Monthly SIP is the gold standard of balance and simplicity.
C. The Core-and-Satellite Portfolio Architecture
Avoid accumulating dozens of mutual funds. An institutional SIP portfolio should follow a focused Core-and-Satellite structure:
- Core Allocation (60%–70%): Low-cost Nifty 50 / Nifty LargeMidcap 250 Index Fund or a disciplined Flexi-Cap Fund (e.g. Parag Parikh Flexi Cap). This forms the stable, compound-generating foundation of your wealth.
- Satellite Allocation (30%–40%): Mid-Cap Fund (e.g. Motilal Oswal Midcap) and a curated Small-Cap Fund (e.g. Nippon India Small Cap) to capture aggressive growth in India's expanding industrial and consumer enterprises.
9. Common Psychological Traps & Mistakes to Avoid
The greatest threat to compound interest is not market volatility; it is human emotion. Avoid these five fatal retail investing errors:
Five Compounding Destroyers
1. Pausing or Stopping SIPs During Market Crashes: When the market drops 20% or 30%, headline panic tempts investors to stop their SIPs. This is the single most destructive mistake in investing: it interrupts Rupee Cost Averaging and prevents you from accumulating units at clearance sale prices. As Charlie Munger famously noted: "The first rule of compounding is to never interrupt it unnecessarily."
2. Portfolio Over-Diversification: Holding 15 different mutual funds does not lower your risk. Most equity mutual funds hold overlapping portfolios of large-cap stocks. Owning more than 3 to 5 funds leads to "diworsification"—diluting your returns while multiplying tracking headaches.
3. Stopping SIPs to "Time" the Market: Attempting to stop an SIP because you believe the market is "too high" and hoping to restart it "at the bottom" consistently fails. Missing just the 10 best trading days across a 15-year period cuts your annualized return in half.
4. Selecting the IDCW (Dividend) Option: Choosing IDCW interrupts compounding by stripping cash out of your mutual fund and subjecting it to full slab-rate income tax. Always select the Direct-Growth option.
5. Neglecting Periodic Portfolio Rebalancing: As small and mid-cap funds rally, their proportion in your portfolio can balloon from 30% to 60%, exposing you to excessive drawdown risk. Rebalance your portfolio once a year to restore your target asset allocation.
10. Statutory Regulatory References & Official Frameworks
The operational rules, mutual fund governance, automated payment mandates, and taxation frameworks referenced in this guide are grounded in official regulatory statutes:
- Securities and Exchange Board of India (Mutual Funds) Regulations, 1996: Master statutory framework governing mutual fund governance, NAV calculation procedures, expense ratio caps, and investor protection standards at SEBI Legal Regulations Portal.
- Association of Mutual Funds in India (AMFI): Official industry repository tracking monthly retail SIP inflows, active folios, and investor education guidelines at AMFI India.
- National Payments Corporation of India (NPCI): Regulatory operating circulars governing recurring e-mandates, National Automated Clearing House (NACH), and UPI AutoPay protocols at NPCI Portal.
- Income-tax Act, 1961 (Sections 45, 111A, 112A, and 115A): Legislative statutes governing capital gains taxation on equity mutual funds and the First-In, First-Out (FIFO) unit redemption framework at the Income Tax Department of India.
- MF Central: The unified mutual fund investor services platform built by SEBI-registered registrars (CAMS and KFintech) at MF Central.
Frequently Asked Questions (Institutional FAQ Desk)
Educational & Regulatory Disclosures
Source Attribution: This masterclass educational guide is produced strictly for investor awareness and capital markets literacy in alignment with SEBI Investor Education and Protection Fund (IEPF) guidelines.
Non-Advisory Mandate & Risk Warning: Digital Arthalaya is strictly an independent financial education portal and is not a SEBI-registered investment advisor or stock broker. IPO bidding and equity trading involve market risk, including potential loss of principal. Readers must conduct their own independent due diligence and read all offer documents carefully before making investment commitments.