SEBI IPO Quotas: Retail 35% vs 10% & HNI Rules Explained (2026) | DA
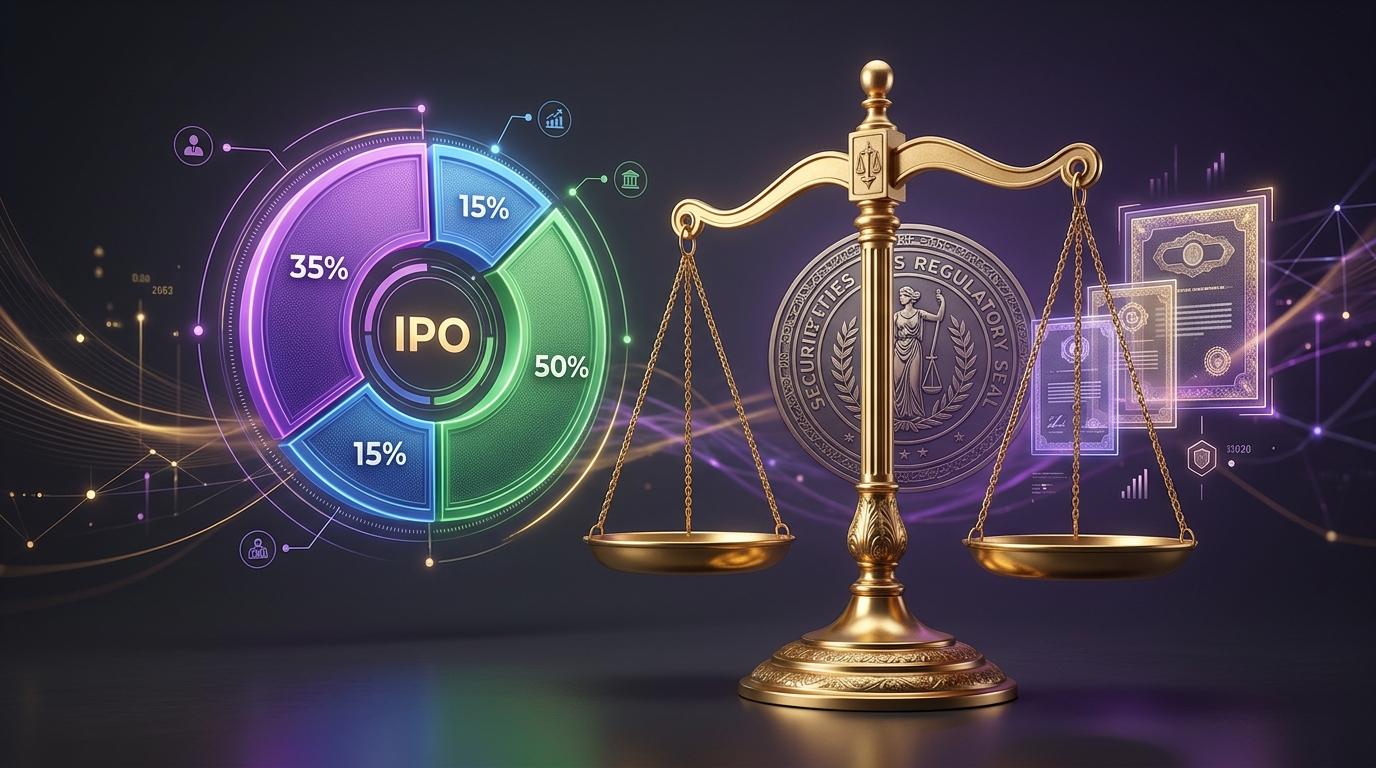
Under the SEBI (Issue of Capital and Disclosure Requirements) Regulations, 2018, every Indian IPO allocates shares according to strict statutory tracks. Profitable companies listing under Regulation 6(1) must reserve a minimum of 35% of the net offer for Retail Individual Investors (RII up to ₹2 Lakh), 15% for Non-Institutional Investors (NII), and up to 50% for Qualified Institutional Buyers (QIB). Conversely, loss-making or tech startup issuers listing under Regulation 6(2) cap the retail quota at just 10%, mandating a 75% QIB allocation to safeguard retail wealth. In oversubscribed retail issues, SEBI's computerized lottery guarantees successful applicants receive exactly one minimum lot, rendering multiple lots under a single PAN mathematically redundant.
When an unlisted corporate issuer announces an Initial Public Offering (IPO) in India, retail market commentary frequently highlights the aggregate issue size—such as a ₹5,000 Crore public offering. However, seasoned primary market participants know that the entire issue is never sold to the public as a homogenous pool. Instead, the securities are partitioned into strictly regulated percentage tranches known as investor reservation quotas.
The architecture of these quotas is not determined arbitrarily by the issuing company or investment bankers. It is codified by statutory federal enactments under the Securities and Exchange Board of India (Issue of Capital and Disclosure Requirements) Regulations, 2018 (SEBI ICDR Regulations). Why do some IPOs offer a generous 35% retail quota while others restrict retail investors to a tiny 10% allocation? How does the 2022 HNI bifurcation into Small HNI (sNII) and Big HNI (bNII) work? And why does bidding for maximum lots in an oversubscribed retail issue provide zero additional lottery probability? This comprehensive 2026 institutional guide breaks down SEBI ICDR Regulations 6(1) and 6(2), analyzes quota allocation math, demystifies Anchor investor lock-ins, and explains the computerized retail lottery mechanism.
1. The Statutory Framework: SEBI ICDR Regulations, 2018
The primary capital market in India operates under the statutory oversight of SEBI. The SEBI ICDR Regulations, 2018 serve as the master rulebook governing how companies raise equity from public markets, structure their Draft Red Herring Prospectus (DRHP), and allocate shares across investor classes:
The Dual Mandate of Primary Market Quota Design
1. Protecting Retail Capital: Individual retail investors do not possess in-house equity research teams, forensic accountants, or direct access to promoter management meetings. SEBI structures IPO quotas to insulate small savers from aggressive corporate balance sheet risks.
2. Institutional Price Discovery: Sophisticated institutional investors (mutual funds, foreign portfolio investors, insurance companies, and pension funds) act as the professional price discovery engine during the book-building process. Their extensive due diligence sets the fair equilibrium price band for the entire market.
2. Regulation 6(1) vs. Regulation 6(2): The Profitability vs. Tech Startup Divide
The single most important factor determining whether an IPO offers a 35% retail quota or a 10% retail quota is whether the issuing corporation satisfies SEBI's historical profitability track record under Regulation 6 of SEBI ICDR:
| Regulatory Issue Track | Eligibility Criteria Thresholds | Retail Quota (RII) | Non-Institutional (NII / HNI) | Institutional (QIB) |
|---|---|---|---|---|
| Track 1: Regulation 6(1) (Profitability Route) | • Net tangible assets ≥ ₹3 Cr in each of preceding 3 yrs • Average operating profit ≥ ₹15 Cr in 3 of 5 yrs • Net worth ≥ ₹1 Cr in each of preceding 3 yrs |
Minimum 35% of Net Offer | Minimum 15% of Net Offer | Maximum 50% of Net Offer |
| Track 2: Regulation 6(2) (Non-Profit / Startup Route) | Cannot satisfy the 3-year profitability criteria (e.g. loss-making tech platforms, high-growth startups, capital-intensive firms). | Maximum 10% of Net Offer (Strict Cap) | Maximum 15% of Net Offer | Minimum 75% Compulsory Allocation |
Why Does SEBI Compress the Retail Quota to 10% Under Regulation 6(2)?
When high-profile technology platforms (such as Zomato, Paytm, Nykaa, or Delhivery) list on the exchange, they often operate with massive accumulated balance sheet losses and unproven unit economics. If retail investors were offered 35% of such issues, aggressive marketing could expose small household savings to devastating capital destruction.
To eliminate this systemic risk, SEBI Regulation 6(2) mandates that at least 75% of the entire IPO must be vetted, underwritten, and subscribed by Qualified Institutional Buyers (QIBs). If institutional asset managers—who possess sophisticated quantitative risk models—are unwilling to purchase 75% of the company, the public issue legally fails. Simultaneously, retail allocation is strictly restricted to a maximum of 10%, ensuring small investors have minimal systemic exposure.
3. The Retail Individual Investor (RII) Quota: Rules & Limits
The Retail Individual Investor (RII) category represents individual domestic citizens applying for personal wealth creation:
- The Statutory Monetary Cap (Up to ₹2,00,000): Regulation 2(1)(yy) of SEBI ICDR defines a retail individual investor as an applicant whose total bid consideration does not exceed ₹2,00,000 across all bid lots. If an applicant submits a bid valued at ₹2,00,050, the application is automatically shifted out of retail into the Non-Institutional (NII) category.
- Exclusive Eligibility for Cut-Off Price: Retail investors and eligible company employees are the *only* market participants legally permitted to bid at the "Cut-off Price". Selecting the cut-off option guarantees that your bid automatically matches the final price discovered by book-running lead managers, preventing bid disqualification if the issue closes at the ceiling of the price band.
- Mandatory Payment via UPI ASBA: Retail applications submitted through registered syndicate brokers must use UPI ASBA, with funds blocked under an administrative bank lien.
4. The 2022 HNI Quota Bifurcation: Small HNI (sNII) vs. Big HNI (bNII)
Historically, the 15% Non-Institutional Investor (NII / HNI) quota was dominated by ultra-wealthy individuals who borrowed hundreds of crores from Non-Banking Financial Companies (NBFCs) for 7 days. Because allotment was executed on a proportionate basis, high-net-worth applicants who applied for ₹500 Crore captured almost all shares, while genuine investors applying for ₹5 Lakh received zero allocation.
To end this speculative arbitrage, SEBI amended the ICDR regulations effective April 2022 (Circular SEBI/HO/CFD/DIL2/CIR/P/2022/45), implementing a strict two-tier HNI quota bifurcation:
The Two Tiers of the Non-Institutional Quota
• Small Non-Institutional Investors (sNII / Small HNI): Applications from ₹2,00,001 to ₹10,00,000. Allocated exactly one-third (33.3%) of the NII quota (representing 5% of the overall IPO). Crucially, allotment is executed via a randomized draw of lots (identical to the retail lottery), ensuring that every successful small HNI applicant receives a minimum allocation lot valued at roughly ₹2 Lakh.
• Big Non-Institutional Investors (bNII / Big HNI): Applications exceeding ₹10,00,000. Allocated two-thirds (66.7%) of the NII quota (representing 10% of the overall IPO). Allotment is also determined by draw of lots, with a minimum allotment size equal to the sNII ticket size (~₹2 Lakh).
• Cut-Off Price Prohibited: Neither sNII nor bNII bidders are permitted to bid at "Cut-Off Price". They must specify an exact bid price (which should always be the upper cap of the price band to avoid rejection).
5. Qualified Institutional Buyers (QIB) & The Anchor Investor Framework
The Qualified Institutional Buyer (QIB) segment comprises professional institutional capital: mutual funds, Foreign Portfolio Investors (FPIs), registered alternative investment funds (AIFs), scheduled commercial banks, insurance companies, and state pension funds:
The Anchor Investor Mechanism
To anchor market confidence prior to public subscription, book-running lead managers can allocate up to 60% of the institutional QIB quota to Anchor Investors exactly one day before the public issue opens. Marquee sovereign funds (e.g., GIC Singapore, Abu Dhabi Investment Authority) and top mutual funds (SBI MF, HDFC MF, ICICI Prudential MF) commit substantial capital at a fixed price.
The Staggered Anchor Lock-In Framework
To prevent anchor investors from immediately dumping shares on listing morning, SEBI enforces a staggered two-stage lock-in schedule:
1. 30-Day Lock-In (50% of Anchor Shares): Exactly 50% of the shares allocated to anchor investors are legally locked in for 30 calendar days from the date of commercial stock exchange listing.
2. 90-Day Lock-In (Remaining 50% of Anchor Shares): The remaining 50% of anchor shares are locked in for 90 calendar days from the listing date.
Market Impact: Market participants closely monitor the 30-day and 90-day post-listing anniversaries, as the sudden release of locked-in anchor shares can increase secondary market supply and induce temporary price volatility.
6. The Computerized Retail Lottery: How Allotment Is Mathematically Decided
A persistent myth among retail investors is that applying for the maximum permitted retail quantity (e.g., 13 lots valued at ₹1,95,000) increases their probability of receiving an allotment in an oversubscribed IPO. Under SEBI regulations, this belief is 100% mathematically false.
Demystifying SEBI Circular CIR/CFD/DIL/1/2012
Prior to 2012, retail allotments were calculated proportionately, meaning wealthy investors bidding for 13 lots received shares while 1-lot bidders got nothing. In 2012, SEBI revolutionized retail allotment by establishing the Maximum Beneficiary Rule:
• Step 1: Total Retail Lots Available: The registrar calculates the total number of minimum lots available in the retail quota (e.g., 1,00,000 minimum lots of 30 shares each).
• Step 2: Compare with Unique Retail Applicants: If 15,00,000 unique retail applicants applied, the retail portion is 15x oversubscribed.
• Step 3: The Randomized Computerized Draw of Lots: Because available lots (1,00,000) are fewer than unique applicants (15,00,000), SEBI mandates an automated computerized lottery. In this lottery, each unique PAN receives exactly one lottery entry.
• The Single Ticket Reality: Whether an applicant bid for 1 lot (₹15,000) or 13 lots (₹1,95,000), their PAN is entered into the computerized draw exactly once. Successful applicants receive exactly one minimum application lot. Applying for extra lots only locks up capital without boosting your probability!
7. Master Comparison: Investor Categories, Limits & Allotment Rules
The following institutional benchmarking matrix details the statutory parameters governing all primary market investor categories on Dalal Street:
| Investor Bidding Category | Application Amount Limit | Statutory Quota Share (%) | Allotment Methodology | Cut-Off Price Permitted? | Mandatory Payment Mode |
|---|---|---|---|---|---|
| Retail Individual (RII) | Up to ₹2,00,000 | Min 35% (Reg 6(1)) / Max 10% (Reg 6(2)) | Randomized Lottery (1 Lot each) | YES (Highly Recommended) | UPI ASBA (via Broker App) |
| Small HNI (sNII) | ₹2,00,001 to ₹10,00,000 | 5% of Total Issue (1/3rd of NII) | Randomized Lottery (~₹2L Lot each) | NO (Must specify price) | UPI ASBA (≤ ₹5L) / Net Banking |
| Big HNI (bNII) | Above ₹10,00,000 | 10% of Total Issue (2/3rd of NII) | Randomized Lottery (Min ₹2L Lot) | NO (Must specify price) | Net Banking ASBA strictly |
| Institutional (QIB) | Institutional Multi-Crore | Max 50% (Reg 6(1)) / Min 75% (Reg 6(2)) | Proportionate Allotment | NO (Electronic book bidding) | Direct ASBA / Institutional clearing |
| Anchor Investors | Minimum ₹10 Crore | Up to 60% of QIB Quota | Discretionary allocation by BRLMs | Fixed Price prior to opening | Direct payment to escrow |
8. Under-Subscription, Spillover & The 90% Minimum Subscription Mandate
Public market conditions can fluctuate sharply during an open bidding window. SEBI ICDR regulations codify exact contingency procedures for under-subscribed categories:
The Inter-Category Spillover Mechanics
If a specific public category is not fully subscribed, SEBI allows unsubscribed shares to spill over to other investor categories that exhibit excess demand:
- Retail Under-Subscription: If the retail quota is only 0.70x subscribed, the remaining 30% unsubscribed shares are re-allocated to the QIB and NII categories (provided there is oversubscription in those segments).
- NII Under-Subscription: Unsubscribed NII shares spill over to QIBs and Retail.
- QIB Deficit (Strict Prohibition): Under Regulation 6(2) (the tech startup route), QIB demand *must* cross 75%. If QIBs fail to subscribe to their minimum 75% quota, the public issue legally aborts—it cannot be saved by retail or HNI oversubscription!
The Statutory 90% Minimum Subscription Mandate (Regulation 45)
Under Regulation 45 of SEBI ICDR, an IPO cannot proceed to allotment unless the net offer to the public achieves an aggregate minimum subscription of at least 90%. If total bidding falls below 90%, the issuer must immediately cancel the issue, and all designated banks must revoke the ASBA liens within 2 business days.
9. Common Disqualification Traps & Rejection Triggers
Every public issue witnesses thousands of retail bid disqualifications. Ensure you avoid these critical compliance errors:
- Duplicate Applications Under One PAN: Submitting one bid through Upstox and a second bid through another broker under the exact same PAN causes the registrar’s automated deduplication engine to reject both applications.
- Category Confusion (Retail vs. HNI): Bidding for ₹2,15,000 under the retail quota will cause instant technical rejection. Any bid exceeding ₹2,00,000 must be submitted under the NII category.
- Third-Party Bank Accounts: Using a UPI ID belonging to a family member whose PAN does not match your Demat account violates the Three-Point Match rule, triggering automated cancellation.
- Failing to Bid at Cut-Off: Bidding at a specific price below the final discovered cut-off price renders your application mathematically invalid.
10. Statutory Regulatory References & Official Frameworks
The statutory allocations, eligibility parameters, lottery mechanisms, and anchor lock-in rules detailed in this institutional guide are anchored in official enactments:
- Securities and Exchange Board of India (SEBI): SEBI (Issue of Capital and Disclosure Requirements) Regulations, 2018 (Regulations 6, 32, 45, and Schedule XIII) at SEBI Official Portal.
- SEBI Retail Allotment Circular: Standardized Allotment Methodology in Public Issues Circular
CIR/CFD/DIL/1/2012at SEBI Circulars. - SEBI HNI Bifurcation Circular: Circular
SEBI/HO/CFD/DIL2/CIR/P/2022/45establishing sNII (₹2L–₹10L) and bNII (> ₹10L) tranches at SEBI Regulations Desk. - National Stock Exchange of India (NSE India): Primary market book-building rules and Basis of Allotment guidelines at NSE India.
- Bombay Stock Exchange (BSE India): Public issue allotment validation protocols at BSE India.
- Ministry of Corporate Affairs (MCA): Companies Act, 2013 (Section 26 to Section 42 governing prospectus and private placement) at MCA Portal.
Frequently Asked Questions (Institutional FAQ Desk)
Educational & Regulatory Disclosures
Source Attribution: This masterclass educational guide is produced strictly for investor awareness and capital markets literacy in alignment with SEBI Investor Education and Protection Fund (IEPF) guidelines.
Non-Advisory Mandate & Risk Warning: Digital Arthalaya is strictly an independent financial education portal and is not a SEBI-registered investment advisor or stock broker. IPO bidding and equity trading involve market risk, including potential loss of principal. Readers must conduct their own independent due diligence and read all offer documents carefully before making investment commitments.